Social Media Post Ideas for Financial Advisors Who Serve Retirees
Retirees read carefully and share what's useful with friends and family. These posts each explain one rule or risk that matters in retirement, with one step to take.
The short answerRetirees respond to posts about the rules that apply to them now, like required minimum distributions, giving from an IRA and protecting their money from scams. Keep each post to one rule and one thing to do.
Five posts for advisors who serve retirees
Post 1
When RMDs start
The post
Required minimum distributions now start at 73 for people born from 1951 through 1959. For those born in 1960 or later, it's 75.
Your first one can wait until April 1 of the next year. After that, each one is due by December 31, which can mean two in one year if you wait.
Details at irs.gov.
Why it works. It clears up an age that changed twice in a few years.
When to post it. Any time, and in the fall before year-end deadlines.
Post 2
Giving from your IRA
The post
If you give to charity, here's a rule worth knowing.
Once you're 70½, you can send money straight from your IRA to a qualifying charity. It's called a qualified charitable distribution. It isn't counted as taxable income, and it can count toward your required distribution.
The money has to go directly to the charity. Check the details with your tax professional.
Why it works. Many retirees give to charity and haven't heard of this rule.
When to post it. October through December.
Get posts like these in your own brand
Type your website. In about a minute Watt writes 3 posts for your firm, with your colors, fonts and logo. Free, no sign-up.
Nothing posts without your approval.
Post 3
Your beneficiaries
The post
An often overlooked part of a retirement plan is the beneficiary forms.
They decide who receives your IRA, your 401(k) and many insurance policies, even if your will says something else.
If it's been a few years, or if your family has changed, take a look this month.
Why it works. It's quick to act on and easy to share with a parent or spouse.
When to post it. Any time.
Post 4
Before you wire money
The post
Scams aimed at retirees can be very convincing.
Four habits that help.
Call back on a number you already know, not one in the message.
Never pay anyone with gift cards.
Slow down if it feels urgent. Real banks and agencies can wait.
Tell someone you trust before you send money.
Share this with someone who might need it.
Why it works. It's protective, timely and very shareable.
When to post it. Any time.
Post 5
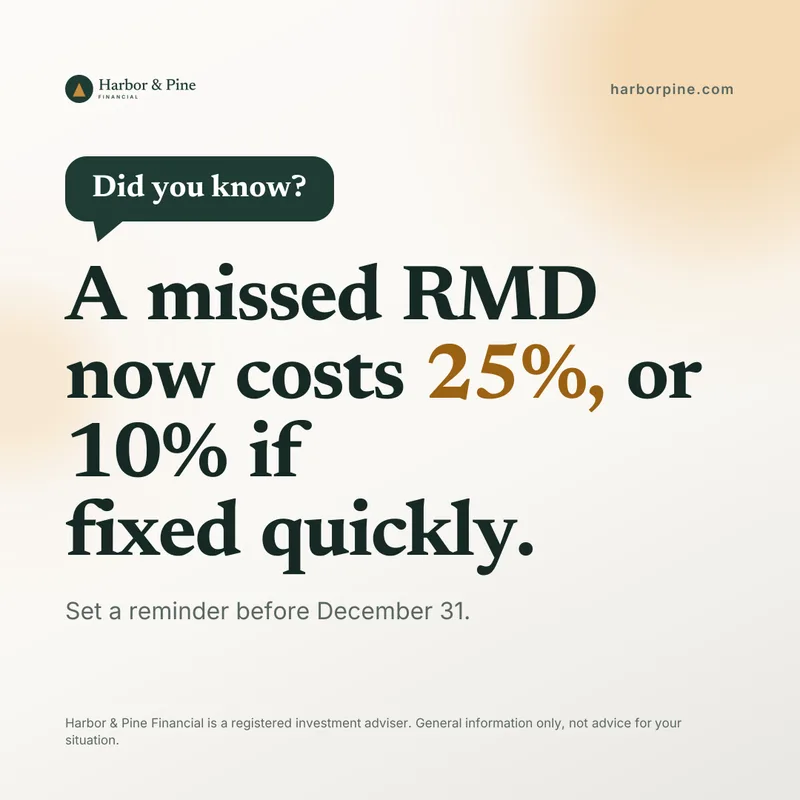
The RMD penalty
The post
Missing a required minimum distribution used to cost 50% of what you should have taken out.
The penalty is now 25%, and it can drop to 10% if you correct it quickly.
Still, the easiest fix is a reminder. Put December 31 on your calendar now.
Details at irs.gov.
Why it works. A real number and a simple action make it worth saving.
When to post it. October through December.
Posting on LinkedIn, Facebook and Instagram
The same square graphic and post work on all three.
LinkedIn shows posts with links to fewer people, so put any link in the first comment.
Links in Instagram captions can't be tapped. Say the link is in your profile.
On Facebook, ending with a question invites replies.
Keep these posts compliant
Use official figures and rules only, and name the source.
Don't give tax conclusions. Point to a tax professional.
Avoid fear-based language about markets or running out of money.
Leave out client stories unless your compliance profile allows them with the required disclosures.
These are general ideas, not compliance approval. Your firm's review decides what goes out.
Get posts like these in your own brand
Type your website. In about a minute Watt writes 3 posts for your firm, with your colors, fonts and logo. Free, no sign-up.
Nothing posts without your approval.
Questions advisors ask
What do retirees want to see from a financial advisor?
Clear explanations of the rules that apply to them now, like required distributions and charitable giving, and help protecting their money from scams.
Can I use these posts as they are?
Use them as a starting point. Change the wording to sound like you, check the figures for the year you post, and run them through your firm's compliance review before they go out.
How do I keep posts for retirees compliant?
Use official rules with their source, avoid tax conclusions and predictions, and keep personal advice for one-on-one conversations.
The graphics on this page were made by Watt for Harbor & Pine Financial, a sample firm. Figures are for 2026 and come from the sources named in each post. Check them for the year you post.